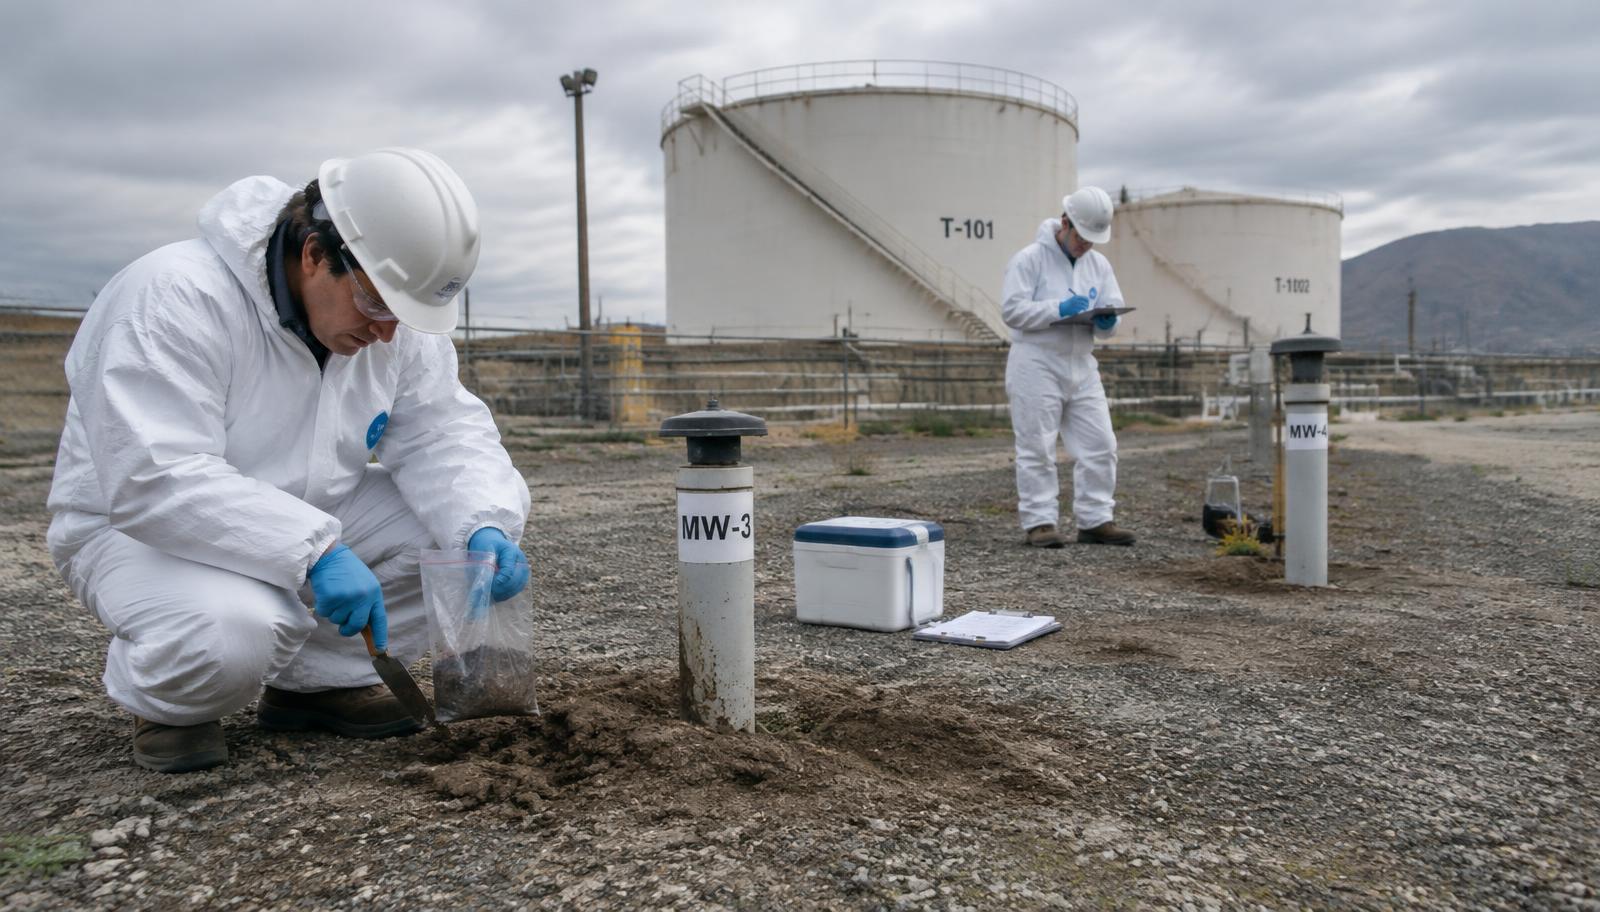
Almost every commercial operation has some degree of pollution exposure, and almost every standard policy excludes it. That is the reason environmental liability insurance in California exists: it pays for cleanup, bodily injury, property damage, and defense costs arising from a release discovered at a property you own or occupy, or caused by work your crew performed for someone else. Owners usually find the gap at the worst possible moment, when a general liability carrier denies a soil or groundwater claim under the pollution exclusion.
Bay Area Business Insurance Solutions is an independent brokerage based in Antioch, CA License #0D90958. We place site pollution, contractors pollution, storage tank, mold, and lender environmental coverage for businesses across Contra Costa County, the East Bay, and the wider Bay Area, and we read the contract or loan document driving the requirement before we market the account.
What Environmental Liability Insurance in California Covers
The two building blocks are easy to keep straight. A site policy covers losses tied to a location you own, rent, or occupy, written on a claims-made basis. A contractors policy covers pollution caused by the services you perform for a third party. Most real programs start with one of those and add the extensions below.
Premises Pollution Legal Liability
Written for the site you own, lease, or occupy. It responds when contamination is discovered at your property or migrates onto a neighbor's, and it pays first-party cleanup on and off site, third-party bodily injury and property damage, legal defense, and in many forms the loss in property value that follows a release. These policies are written on a claims-made basis, so the date your coverage starts and any retroactive date matter as much as the limit.
Contractors Pollution Liability
Site policies follow the property; contractors policies follow the work. If your crew cuts an unmarked fuel line, disturbs contaminated soil, spreads silica or lead dust, or lets a slurry wash into a storm drain, this is the coverage that answers. It can be written on a practice basis for everything you do in a year or on a project-specific basis for a single job, which is usually how owner and general contractor insurance exhibits are worded.
Combined General Liability and Pollution Forms
Standard commercial general liability forms carry a broad pollution exclusion, which is where most owners get surprised. Several carriers now write a combined form that puts ISO-based general liability and site, products, contractors, and transported-cargo pollution coverage in one policy. For a small or mid-sized operation that avoids the coverage gap that opens between two separate policies and two separate claims adjusters.
Transportation and Non-Owned Disposal Sites
Your liability does not end at the gate. A spill from your truck on the way to a facility, or a disposal site that is later named a cleanup site, can both come back to you as a generator. Transportation and non-owned disposal site extensions pick up those exposures, and they are commonly the two endorsements missing from an otherwise reasonable environmental program.
Storage Tank Liability
Above-ground and underground tanks carry both a real leak exposure and a paperwork one. A storage tank policy covers third-party claims and corrective action for a release, and the carrier can issue the certification used to satisfy state and federal financial responsibility rules for tanks. Fueling operations, fleet yards, generators at data and medical facilities, and older industrial parcels all fall here.
Indoor Air Quality, Mold, and Legionella
Mold and bacteria claims are excluded almost everywhere else and remain an expensive area of litigation, especially for apartment owners, HOAs, schools, hotels, and care facilities. An indoor air quality policy covers bodily injury, property damage, legal expense, and building cleanup from mold, Legionella, and other biological conditions found on a covered location.
Lender and Transaction Coverage
Environmental coverage is frequently a condition of a purchase and sale agreement, a lease, or a loan rather than something a business shops for on its own. Secured creditor policies protect a lender against known and unknown contamination at collateral property, including diminution in the value of that collateral. Buyers and sellers use site policies to close the gap left by a Phase I or Phase II report and to get a deal to closing.
Closure Assurance and Excess Limits
Permitted facilities can be required to prove financially that they can close a site and monitor it afterward; a closure and post-closure policy is usually the cheapest way to satisfy that requirement. At the other end, follow-form excess environmental limits sit above a primary policy for accounts that have a contract, a lender, or an agency asking for more than the primary carrier will write.
California Regulators and East Bay Site Risk
Cleanup in this state rarely involves one agency. The San Francisco Bay Regional Water Quality Control Board oversees groundwater and discharge issues, the Department of Toxic Substances Control handles hazardous waste and contaminated site cleanup, county environmental health departments run the Certified Unified Program Agency duties for tanks and hazardous materials business plans, and the air district gets involved with dust and emissions during demolition. Proposition 65 warning obligations can follow a release, and a single discovery can produce parallel orders from more than one of those bodies. Defense and consultant costs start accruing long before anyone agrees who is responsible.
Geography matters here too. The industrial corridor from Richmond through Martinez, Concord, Pittsburg, and Antioch has generations of refining, manufacturing, and rail use behind it, so redevelopment projects routinely hit legacy soil and groundwater contamination that no current owner created. Sites near the Delta and the Bay have shallow groundwater, which shortens the distance a plume travels before it becomes a neighbor's problem. Older commercial buildings carry asbestos, lead paint, and vapor intrusion questions, and fire-season and seismic events can turn a contained condition into a release. Under California law liability for contamination generally attaches to the property, not to the person who caused it, which is why lenders and buyers ask for this coverage even on clean-looking parcels.
Operations We Write Environmental Coverage For
- General, demolition, and excavation contractors
- Environmental, remediation, and abatement firms
- Manufacturers and industrial property owners
- Fuel, fleet, and storage tank operations
- Apartment, HOA, and commercial property owners
- Waste haulers, recyclers, and transfer operations
- Real estate buyers, sellers, and secured lenders
- Agricultural, winery, and food processing sites
Serving Property Owners and Contractors Across Contra Costa and the Bay Area
We work with owners, contractors, lenders, and facility managers in Walnut Creek, Concord, Pleasant Hill, Martinez, San Ramon, Danville, Antioch, Richmond, and throughout the Bay Area. Send us the insurance exhibit, loan condition, or Phase I finding you are working against and we will tell you which form actually answers it and what limit the market will support. Contractors should also review our notes on contractors general liability, and property owners with grounds or chemical exposure may want to read about landscaping and gardening coverage as well.
Get an Environmental Liability Quote
Independent brokers based in Antioch placing pollution and environmental coverage across California. CA License #0D90958.