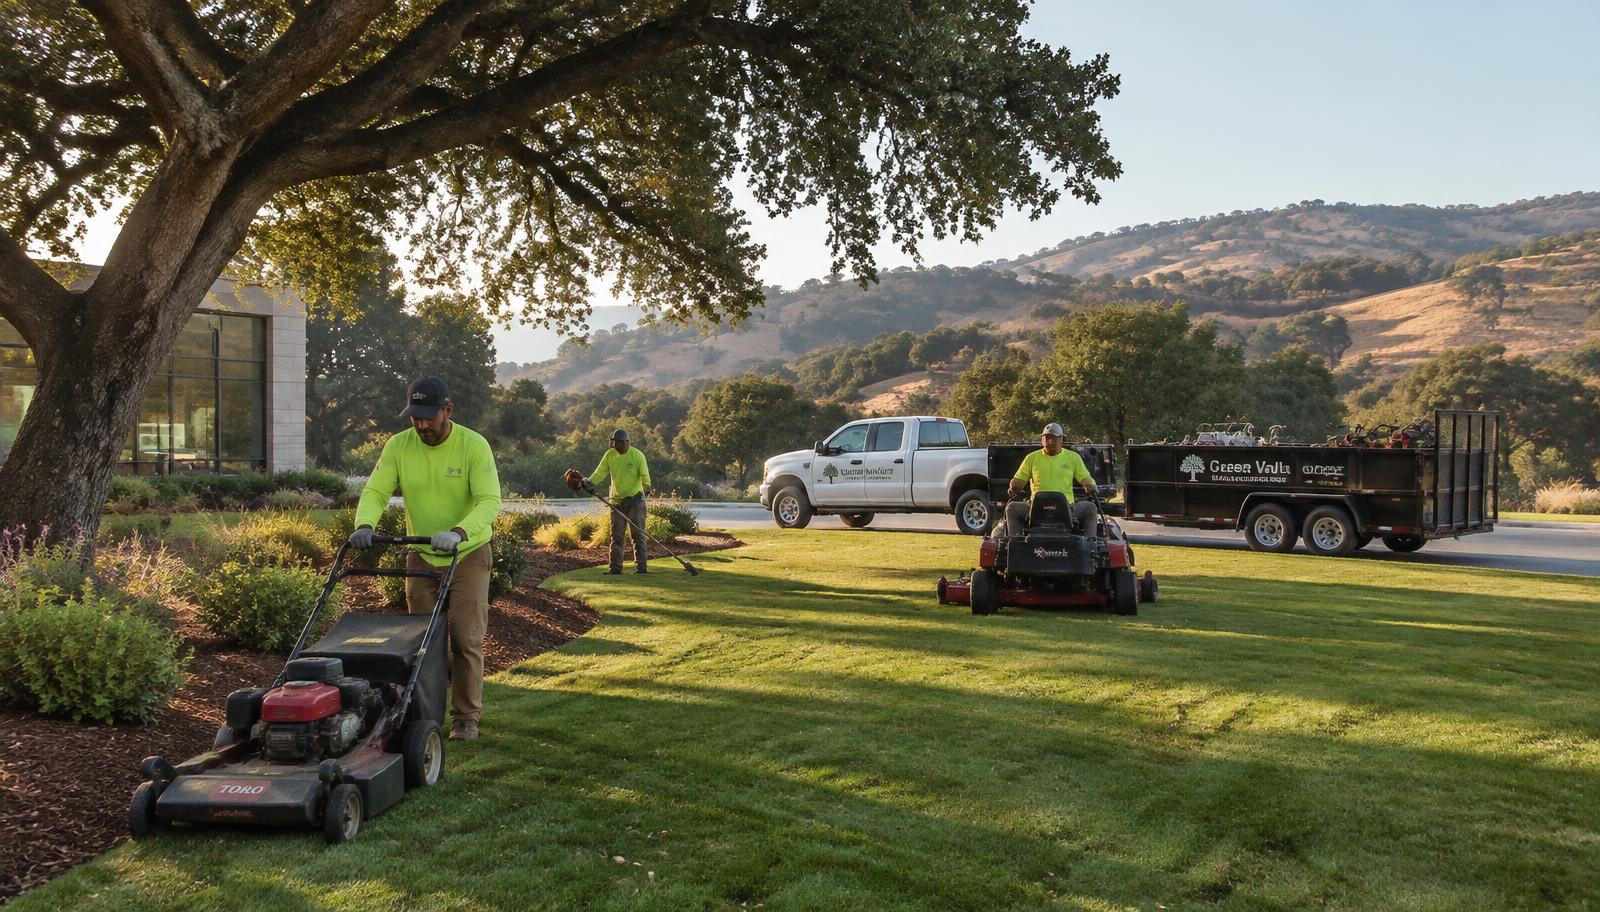
A landscape company runs a fleet, a crew, and a yard full of equipment, and it does all of it on property that belongs to someone else. That is why landscaping insurance in California is rarely one policy. The claim that closes a season is usually a mower-thrown rock through a windshield, a trailer of stolen equipment, a heat illness citation, or a trencher through a utility line, and those four losses sit under four different coverages.
Bay Area Business Insurance Solutions is an independent brokerage based in Antioch, CA License #0D90958. We write grounds maintenance companies, design-build landscape contractors, irrigation and hardscape crews, and tree services across Contra Costa County, the East Bay, and the wider Bay Area, and we build the program around your crew size, your equipment schedule, and the contracts you are trying to win.
What Landscaping Insurance in California Should Cover
Most landscape accounts we review are missing the same three things: the trailer is not scheduled, equipment is covered only while it sits in the yard, and the chemical exposure was never endorsed. A complete program closes those gaps before a claim finds them.
Commercial General Liability
Most of what goes wrong on a landscape job involves someone else's property or someone else's body. A rock thrown by a mower cracks a windshield, a trencher clips an unmarked irrigation or utility line, a client trips on a hose left across a walkway. General liability answers those claims and pays defense costs. It is also the policy your commercial clients, HOA boards, and property managers will ask to see before they let a crew on site, so the certificate needs to match what the contract actually requires.
Workers' Compensation
Landscaping is one of the higher-rated classes in California, and for good reason: crews handle blades, chainsaws, ladders, and heavy material in summer heat. Workers' comp pays medical care and lost wages for lacerations, strains, falls, and heat illness. Because rates are high, the controls matter. A documented heat illness prevention plan, bilingual safety training, equipment guarding, and an active return-to-work program move your experience modification rate, which drives premium far more than shopping carriers each year.
Commercial Auto for Trucks and Trailers
Your trucks tow loaded trailers through residential streets and onto job sites every day, and trailers are where coverage most often falls apart. The trailer itself needs to be scheduled, hitched liability needs to extend to it, and drivers need to be listed and pulled for MVRs. We also look at hired and non-owned auto for the times an employee runs for materials in a personal vehicle, which is a gap on a surprising number of landscape accounts.
Equipment and Inland Marine
Mowers, blowers, trimmers, stump grinders, skid steers, and hand tools travel and sit unattended, which puts them outside a standard property policy for most of their life. Inland marine covers them in transit, at the job, and overnight in the yard, on a scheduled or blanket basis. Theft from trailers is the dominant loss in this class across the East Bay, so we pay attention to deductibles, unattended-vehicle conditions, and whether rented or leased equipment is included.
Herbicide and Pesticide Liability
Applying chemicals introduces an exposure that general liability often excludes or sublimits. Drift onto a neighboring garden, an over-application that kills established plantings, or a complaint about exposure near a school or playground can all turn into claims. If you hold a Qualified Applicator License or work under a licensed applicator, the policy should carry an appropriate pesticide and herbicide endorsement with a limit that reflects the properties you treat.
Property, Yard, and Installation Floater
Your shop, yard, fencing, irrigation stock, plant material, and stored fuel all carry value. An installation floater covers materials you have purchased but not yet installed, which matters on larger hardscape and irrigation jobs where thousands of dollars in pavers, controllers, or specimen trees sit on site for days before they become the owner's property.
Employment Practices Liability (EPLI)
Seasonal hiring, piece-rate and prevailing-wage questions, meal and rest break records, and heat recovery periods make landscaping a frequent target for wage-and-hour actions in California. Under PAGA a timekeeping error that affects the whole crew can become a six-figure exposure. EPLI funds the defense and settlement of harassment, discrimination, and wrongful termination claims; wage-and-hour defense is usually a separate sublimit worth asking for by name.
Commercial Umbrella
Tree work, work near roadways, and contracts with municipalities, school districts, and property management firms often require limits above what a primary policy carries. An umbrella sits over general liability, auto, and employers liability, and in practice it is the cheapest way to meet a five-million-dollar contract requirement without rewriting every underlying policy.
California Licensing, Heat Rules, and East Bay Risk
Anything beyond routine mowing and gardening generally requires a C-27 Landscaping license from the Contractors State License Board, and installation work that touches grading, drainage, or structures can pull in other classifications. Chemical application requires licensing through the Department of Pesticide Regulation and county agricultural commissioner registration. Underwriters check both, and carriers price an unlicensed or mismatched operation as a much worse risk than it usually is. Keeping your license classification aligned with the work you actually sell is one of the quiet ways to keep your rate down.
Cal/OSHA's heat illness prevention standard is the compliance issue that bites hardest in the inland East Bay. From Antioch and Brentwood through Concord and Walnut Creek, summer afternoons routinely clear 95 degrees, which triggers shade, water, cool-down, and high-heat procedure requirements plus written training in the language your crew speaks. Fire season adds a second layer: spark-arrestor rules, red flag restrictions on mowing dry grass, and weed abatement contracts that carry their own liability. Add the region's equipment theft rate and rising replacement costs on trucks and mowers, and the two most valuable changes we usually make on a landscape account are scheduling the equipment honestly and documenting the safety program.
Landscape Operations We Insure
- Residential and commercial grounds maintenance
- Landscape design and installation contractors
- Irrigation installation, repair, and controller service
- Hardscape, paver, retaining wall, and masonry crews
- Tree trimming, pruning, and arborist services
- HOA and property management grounds contracts
- Weed abatement and fire-fuel reduction crews
- Holiday lighting, seasonal color, and cleanup services
Serving Landscape Contractors Across Contra Costa and the Bay Area
We work with landscape and gardening companies in Walnut Creek, Concord, Pleasant Hill, Martinez, San Ramon, Danville, Antioch, Richmond, and throughout the Bay Area. Whether you run two trucks on residential routes or a twenty-person crew under HOA and municipal contracts, we can review your certificates against what your contracts require, benchmark your workers' compensation rate against the class, and market the account to carriers that write this work willingly. If you also handle general contracting work or carry a large payroll, it is worth reading our notes on California workers' compensation as well.
Get a Landscaping Insurance Quote
Independent brokers based in Antioch writing landscape, gardening, and grounds maintenance accounts across California. CA License #0D90958.