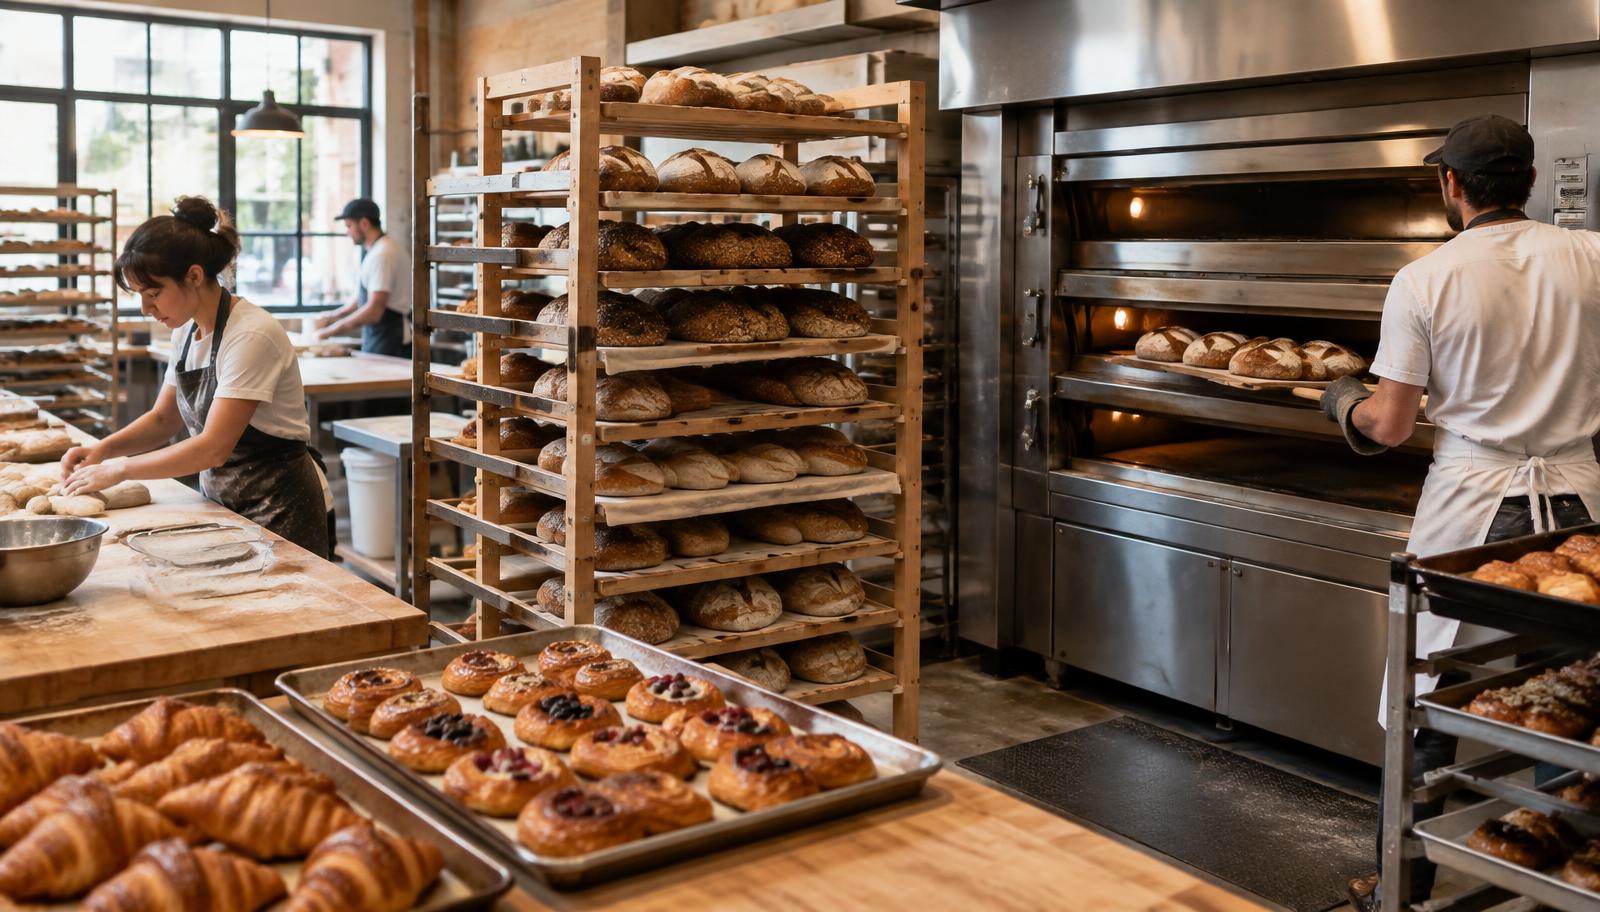
We write bakery insurance for Antioch shops from our office right here in town — retail counters, pastelerías, cake decorators and the wholesale bakehouses supplying restaurants across East County. The coverage questions are practical: what happens if the oven quits, if a customer reacts to an allergen, or if a decorator's wrist gives out mid-season.
Because we are local, we can walk the shop rather than quote off a form. That matters when equipment values and actual production hours drive most of the premium.
What bakery insurance should include
Bakeries sit between retail and light manufacturing, and the insurance should reflect both. You need general liability for the front of house, property at replacement cost for ovens, proofers, mixers and refrigeration, and product liability that responds if an allergen makes it into the wrong box — the claim most likely to become expensive.
If you sell wholesale to grocers, restaurants or coffee shops, check the certificate requirements in those contracts before renewal. Additional insured status and waivers of subrogation are routinely demanded and just as routinely missing.
Ovens, mixers and the cost of downtime
A deck oven or rack oven going down is not just a repair bill; it is days of lost production during the only hours that matter. Equipment breakdown pays for the repair, and business income with a short waiting period pays for the sales you could not make. Ask what the waiting period is — a 72-hour clause on a bakery is close to useless.
Workers' compensation in a hot, early-shift kitchen
Burns, slips on flour dust, and shoulder and wrist strain from repetitive mixing and lifting drive most bakery claims. Crews start before dawn, often short-staffed, which is exactly when injuries happen. Accurate class codes and a documented safety routine are the two levers that move your premium in the direction you want.
Spoilage, contamination and recall
Refrigeration loss ruins dairy, fillings and finished product. Contamination and recall coverage goes further, paying to pull product and notify customers when something goes wrong after it leaves your door. Most bakery package policies include a token spoilage limit and no recall coverage at all.
What we see in Antioch
East County heat is hard on refrigeration and on staff. Summer temperatures over 100 degrees mean walk-ins run constantly, so spoilage and equipment breakdown coverage earn their keep, and Cal/OSHA heat illness rules apply to crews loading and unloading outdoors.
Wholesale accounts are the other Antioch pattern. If you supply restaurants or grocers, their contracts usually require additional insured status and a product liability limit specified in writing — get those endorsements quoted before you sign the account.
Questions Antioch owners ask us
What does bakery insurance cost in Antioch?
A small retail bakery typically runs a few thousand dollars a year for liability and property, with workers' compensation quoted off payroll on top. Ovens, production volume and wholesale contracts push it up from there.
Am I covered if an allergen gets into a product?
Product liability responds to bodily injury from a product you made. Labeling practices and separation procedures affect both the claim outcome and your pricing, so document them.
Does insurance pay if my oven breaks down?
Equipment breakdown pays for the repair or replacement, and business income covers lost sales during the outage. Check the waiting period — a long one makes the coverage nearly useless for a bakery.
Get a bakery quote for your Antioch business
Tell us your equipment list, annual sales and payroll and we'll benchmark your current coverage against what local bakeries are actually paying. We are an independent brokerage based in Antioch, serving Contra Costa County and the wider Bay Area. CA License #0D90958.
Other cities we write this coverage in
See our full Bakery & Commercial Baking Insurance overview.